THE COMPLETE LAS VEGAS HOMEBUYER'S GUIDE
Buying a Home in Las Vegas: From Your First Question to Your Closing Day.
A practical, step-by-step guide to financing, searching, evaluating properties, making offers, negotiating terms, and closing on a home in Las Vegas, Henderson, North Las Vegas, and the surrounding communities.
Interactive Guide Navigation
Your Homebuying Roadmap
Eight stages take you from your first question to your closing day. Choose a stage to jump straight to it.
01 | Prepare to Buy
Before You Search, Get Clear on What You Need.
A successful home purchase begins before the first showing. Understanding your goals, timeline, financial comfort zone, and priorities helps prevent expensive compromises later.
Before you tour a single home, work through these ten considerations:
- Why you want to buy.
- How long you expect to own the property.
- Your preferred monthly housing payment.
- Available funds for upfront costs.
- Desired home size and features.
- Lifestyle and commuting considerations.
- Community preferences.
- HOA restrictions and fees.
- Future resale considerations.
- Timing and flexibility.
Decision Tool
Your Homebuying Priorities
Sort every feature you can imagine into three categories before you start touring:
Must Have
Requirements that materially affect whether the home works.
Would Like
Preferences that improve the experience but are negotiable.
Deal Breakers
Conditions or restrictions that make a property unsuitable.
Separating wants from requirements before touring keeps the search honest. When a home is measured against your true requirements first, the preferences that would be nice to have stay in perspective, and you avoid falling for a property that cannot actually work for your life.
The Lockhart Method™ Connection: Diagnose
Steve helps identify the buyer's objectives, constraints, and priorities before developing the purchase strategy.
02 | Understand Financing
Know Your Numbers Before You Fall in Love With a Home.
The purchase price is only one number in the transaction. Understanding the terms below before you tour keeps the process clear and the decisions grounded.
Mortgage prequalification
A quick estimate of what you might be able to borrow, based on the income, debts, and assets you report. It is a useful starting point, not a commitment from a lender.
Mortgage pre-approval
The verified step: the lender reviews your credit, income, assets, and debts and issues a letter for a specific loan amount. Sellers and listing agents expect to see it before an offer.
Final loan approval
The lender’s final underwriting decision after the home is under contract, once the appraisal, title work, and any remaining conditions are satisfied.
Purchase price
The amount you agree to pay for the home.
Down payment
The portion of the purchase price you pay from your own funds at closing; the rest is financed.
Loan amount
The portion of the purchase price you borrow. It is the purchase price minus your down payment, plus any financed costs allowed by the loan program.
Interest rate and APR
The interest rate is the cost of borrowing, expressed as a percentage of the loan. The APR includes the rate plus most lender fees, giving a fuller picture of the loan’s cost.
Principal and interest
Principal is the amount you borrowed; interest is the cost of borrowing it. Together they make up the base of your monthly mortgage payment.
Property taxes
Annual taxes levied on the property, typically collected into an escrow account with your mortgage payment.
Homeowners insurance
Insurance that protects the home and your belongings. Lenders require it, and it is commonly paid through escrow.
Mortgage insurance, where applicable
Insurance that protects the lender when your down payment is below a program’s threshold. It applies to some conventional loans and to FHA loans, and is not required on VA loans.
HOA assessments
Monthly or periodic dues paid to the homeowners association for shared amenities, maintenance, and reserves.
Closing costs
The lender, title, escrow, recording, and prepaid costs paid at closing, separate from the down payment.
Cash reserves
Money you keep available after closing. Lenders often review reserves to confirm you can cover several months of mortgage payments.
Financing Categories Compared
Each financing category has typical characteristics, eligibility considerations, and tradeoffs. Qualification is never guaranteed: it depends on your lender, credit, income, debts, and the specific program. Rates, program limits, and assistance eligibility change over time, so confirm current details with a lender before planning around them.
Conventional Financing
Offered by private lenders and not insured by a federal agency. Down payment and pricing depend on your credit, income, and the lender. Private mortgage insurance may apply when the down payment is below the lender’s threshold. Tradeoff: terms vary with your financial profile.
FHA Financing
Insured by the federal government and available through approved lenders. Designed for buyers with smaller down payments or more flexible credit requirements. Tradeoff: mortgage insurance premiums generally apply for the life of the loan.
VA Financing
Available to eligible veterans, active duty members, and qualifying National Guard and Reserve members. Offers no down payment on most purchases and no private mortgage insurance, with a one-time funding fee. Tradeoff: eligibility, occupancy, and property requirements apply.
USDA Financing, Where Eligible
Available in designated rural and some suburban areas for eligible buyers, with low down payment options. Tradeoff: the property must be in an eligible area and program requirements apply.
Before You Close
What Cash Might I Need Before Closing?
Beyond the down payment, several costs arrive before or at closing:
Earnest money
A good-faith deposit held in escrow after your offer is accepted. It is generally credited toward your transaction obligations at closing, subject to the contract terms.
Inspections
Fees paid to licensed inspectors for the home inspection and any specialized inspections you choose.
Appraisal charges
The fee for the lender’s appraisal of the property, often paid at or before closing.
Down payment
The portion of the purchase price you pay from your own funds.
Prepaid expenses
Upfront payments for items like homeowners insurance and property taxes that begin at closing.
Closing costs
Lender, title, escrow, recording, and other fees paid at closing, separate from the down payment.
Hypothetical example: Assume a purchase price of $500,000, a down payment of $100,000 (20 percent), and a loan amount of $400,000. Assume closing costs of $12,000 paid at closing. The purchase price is $500,000, but the cash you need at closing is the $100,000 down payment plus $12,000 in closing costs, or $112,000 total. The $400,000 loan amount is what you finance and repay over time. All figures are hypothetical and for illustration only; actual amounts depend on the property, the loan program, and the lender.
A lender's maximum approval amount is not necessarily your comfortable budget. Approval reflects what you can qualify for; your budget should also reflect your lifestyle, savings goals, and the full costs of ownership.
The Lockhart Method™ Connection: Reposition
Prepare the buyer financially and strategically before competing for a property.
03 | Search for Homes
Search With a Strategy, Not Just a Price Range.
A price range is a filter, not a strategy. Evaluate every candidate home against these eleven factors:
- Location.
- Property type.
- Home size and layout.
- Age and condition.
- Neighborhood characteristics.
- HOA and community restrictions.
- Amenities.
- Commute and accessibility.
- New construction versus resale.
- Ownership costs.
- Resale potential.
Community Resources
The neighborhood decision comes before the house decision. Explore the communities that make up the Las Vegas Valley:
What to Watch in the Listings
New listings show you what is entering the market, price reductions can reveal motivated sellers or overpriced homes, back-on-market properties may signal a transaction that did not work out for reasons worth understanding, and property history, including prior sales and listing changes, adds context to the asking price.
The Lockhart Method™ Connection: Activate Demand
Use targeted property searches and available market intelligence to identify suitable opportunities.
04 | Tour and Evaluate
Look Beyond the Photos.
Photos show the best angle at the best moment. The tour is where you test whether the home actually works. Observe these thirteen points at every showing:
- Roof and visible exterior condition.
- Signs of water intrusion.
- HVAC age and apparent condition.
- Windows and insulation considerations.
- Plumbing and electrical observations.
- Layout functionality.
- Natural lighting.
- Noise and surrounding conditions.
- Parking and storage.
- Yard maintenance.
- Solar equipment and associated obligations.
- HOA rules.
- Potential repair and improvement costs.
A buyer walkthrough is not a substitute for a qualified home inspection. Independent inspectors are licensed professionals hired by you, and they are not employees of Steve or his brokerage.
Checklist
Five Questions to Ask After Every Showing
- 1 Does this home meet our non-negotiable needs?
- 2 What concerns require professional investigation?
- 3 How does the price compare with relevant properties?
- 4 What will ownership realistically cost?
- 5 Would this home still make sense if we owned it for several years?
Emotional enthusiasm is part of buying a home, and it is not a problem by itself. The risk is when enthusiasm replaces evaluation. Tour with your checklist, ask the five questions after every showing, and let the objective picture guide the decision.
05 | Make an Offer
The Best Offer Is Not Always the Highest Offer.
A strong offer is built from more than a number. Evaluate these fourteen factors together:
- Comparable closed sales.
- Current competing listings.
- Property condition.
- Listing history.
- Days on market.
- Seller circumstances when legitimately known.
- Financing strength.
- Earnest money.
- Closing timeline.
- Inspection provisions.
- Appraisal considerations.
- Seller concessions.
- Contract contingencies.
- Buyer-agent compensation arrangements where relevant.
How to Read an Offer
Price Is Only One Part of the Negotiation.
A purchase agreement combines price, financing, timing, contingencies, responsibilities, and risk allocation.
Asking Price
What the seller is requesting.
Market Evidence
What comparable transactions and current competition suggest.
Buyer Value
What the property is worth to the buyer given its condition, costs, suitability, and alternatives.
Hypothetical example: Assume a home listed at $500,000. Offer A is $510,000 with no seller concessions. Offer B is $505,000 with a $10,000 seller credit toward the buyer's closing costs. On price alone, Offer A looks stronger, but the buyer in Offer B effectively pays $495,000 after the credit, and the seller's net outcome depends on the concessions, timeline, and contingencies each offer carries. Which offer is better depends on the buyer's cash position, financing, and the seller's priorities. These figures are hypothetical and for illustration only. No offer structure guarantees acceptance; sellers weigh price, terms, and certainty together.
The Lockhart Method™ Connection: Negotiate & Close
Steve evaluates price and terms together to help buyers make informed offers.
06 | Navigate Due Diligence
What Happens After Your Offer Is Accepted?
Acceptance starts the clock on a coordinated set of activities. These commonly follow contract acceptance:
- Earnest money delivery.
- Contract and deadline review.
- Seller disclosures.
- Home inspection.
- Specialized inspections when appropriate.
- Repair requests or negotiations.
- Appraisal.
- Lender underwriting.
- Title review.
- HOA and common-interest community document review where applicable.
- Insurance arrangements.
- Final loan conditions.
- Closing coordination.
Nevada Resale Packages for Common-Interest Communities
When the home is part of a common-interest community, an HOA, Nevada law (NRS 116.4109) requires the seller to provide the buyer a resale package at the seller's expense. The package includes the declaration, bylaws, rules, the association's budget and financial information, the status of unpaid assessments, and other disclosures. The association generally must provide the package within 10 calendar days of a written request, and the package remains effective for 90 calendar days. Under NRS 116.4109, a buyer may cancel the purchase contract without penalty until midnight of the fifth calendar day after receiving the resale package. These rules apply to covered common-interest community sales, and your contract may include its own review and deadline provisions. Review your contract carefully and consult qualified counsel for your specific situation.
Common Risks Buyers Should Understand
- Inspection discoveries
- Appraisal gaps
- Financing delays
- Title issues
- Insurance concerns
- HOA restrictions
- Missed contractual deadlines
Inspections identify issues for evaluation; they do not guarantee the future condition of the property.
Steve coordinates the process with your lender, title and escrow professionals, inspectors, and other relevant parties, keeping communication clear and deadlines on track, while remaining within the scope of licensed real estate representation. He does not perform inspections, underwrite loans, or provide legal advice; those roles belong to the licensed professionals who serve you.
The Lockhart Method™ Connection: Control the Experience
Emphasize communication, deadline awareness, coordination, and informed decision-making.
07 | Prepare for Closing
Know What to Expect Before Closing Day.
The final stretch is about details and deadlines. Expect these ten elements in the days before and on closing day:
- Final financing review.
- Closing Disclosure for applicable mortgage transactions.
- Verification of required funds.
- Homeowners insurance.
- Final walkthrough.
- Title and escrow coordination.
- Document signing.
- Recording.
- Utility arrangements.
- Possession timing.
Signing documents, funding, recording, and possession are related but distinct milestones. Signing completes the paperwork, funding moves the money, recording makes the transfer official in the public records, and possession is when you receive the keys. Keys are not automatically released immediately after signing; possession follows the terms of your contract and the escrow process.
Checklist
Before Closing
- Verify required funds and payment instructions independently through a trusted contact method.
- Review final documents.
- Confirm walkthrough arrangements.
- Understand possession terms.
- Coordinate utilities and moving arrangements.
Security Warning
Real Estate Wire Fraud Is Real
If you receive wiring instructions by email, text, or phone, do not rely on them without verification. Independently confirm the instructions through a trusted contact method, such as a phone number you know is correct, before transferring any funds. If you suspect fraud, contact your escrow officer and your financial institution immediately.
08 | Close and Move In
Closing Is a Milestone. Ownership Is the Next Chapter.
Once the transaction records, ownership begins. Work through these ten ownership topics:
- Confirmation of recording and possession.
- Key and access transfer.
- Utilities.
- HOA account setup.
- Home warranty documentation, if applicable.
- Maintenance records.
- Emergency contacts.
- Property tax and insurance awareness.
- Home maintenance planning.
- Document retention.
Checklist
Your First 30 Days as a Homeowner
Access
- Confirm all keys, remotes, and garage codes.
- Change locks and entry codes.
Safety
- Test smoke and carbon monoxide detectors.
- Locate the water shutoff and the breaker panel.
- Check fire extinguishers.
Maintenance
- Schedule a seasonal HVAC check.
- Review irrigation and exterior systems.
- Note warranty contacts for appliances and systems.
Documentation
- Keep the closing file, deed, and title policy in a safe place.
- Save appliance manuals and warranties.
Financial organization
- Set up property tax and insurance reminders.
- Confirm HOA account setup.
- Review your first utility bills.
Steve does not provide legal, tax, lending, or inspection services. For those matters, work with the licensed professionals who serve your transaction.
Special Pathways
Your Buying Strategy Should Reflect Your Situation.
Every buyer starts from a different place. Choose the pathway that fits your situation and go deeper on the details that matter to you.
First-Time Buyers
Financing, preparation, upfront costs, and navigating a first purchase.
ExploreMilitary & VA Buyers
VA financing considerations, relocation, and military household needs.
ExploreRelocating Buyers
Remote planning, community research, and practical transition considerations.
ExploreNew Construction Buyers
Builder contracts, incentives, upgrades, timelines, and representation.
ExploreLuxury Buyers
Property evaluation, privacy, community considerations, and complex negotiations.
ExploreReal Estate Investors
Acquisition analysis, operating costs, rental assumptions, and investment risk.
ExploreThe Lockhart Method™ for Buyers
A Process Built Around Better Decisions.
The same five phases bring structure across financing, property search, evaluation, negotiation, and closing: Diagnose clarifies your goals and constraints, Reposition strengthens your financial position, Activate Demand targets the right opportunities, Control the Experience keeps evaluation and due diligence organized, and Negotiate & Close brings price and terms together.
01
Diagnose
02
Reposition
03
Activate Demand
04
Control the Experience
05
Negotiate & Close
Frequently Asked Questions
Las Vegas Homebuying Questions, Answered.
Straight answers to the questions buyers ask most. Where an answer depends on your lender, loan program, contract terms, or Nevada law, the answer says so.
How much money do I need to buy a home in Las Vegas?
Two buckets: the down payment and the cash to close. Down payment requirements depend on the loan program, and closing costs are separate from the down payment. Your lender can model the exact figure for your price range and program. See the financing section above and the Ask Steve answer on down payments in Las Vegas.
Down payment basics in Las Vegas What credit score is required to purchase a home?
There is no single required score. Conventional, FHA, and VA programs each have their own guidelines, and lenders weigh income, debts, and assets alongside credit. A lender can tell you where you stand before you tour.
Credit score questions, answered Can I buy a home with a small down payment?
Yes, depending on the program. FHA and some conventional programs allow smaller down payments, and eligible VA buyers may finance with no down payment. Program details and lender requirements vary. See the financing section above.
How long does mortgage pre-approval last?
Pre-approval letters are typically valid for a limited window, often around 60 to 90 days, depending on the lender. Check the expiration date on your letter and refresh it if your search runs longer.
Pre-qualification vs. pre-approval Should I buy now or wait?
That depends on your goals, timeline, finances, and the market conditions that apply to your situation. No one can predict the market. The right question is whether buying fits your life and budget now, and a strategy conversation can help you decide.
Is new construction better than resale?
Neither is automatically better. Compare the complete price, timeline, incentives, and ownership costs of both. See the search section above and the Ask Steve answer on new construction versus resale.
New construction vs. resale Do I need an agent when buying from a builder?
Yes, and your agent should be registered at your first visit to the community. The on-site agent represents the builder, and builder policies usually require registration at first contact for your agent to be compensated.
Agents and new construction How do I know whether a home is overpriced?
Compare it with the closed sales that truly compare: similar homes in the same community, adjusted for condition, updates, view, and lot. See the offer section above.
What happens if the inspection reveals problems?
It depends on the findings and your contract. Significant issues can lead to repair requests, a price adjustment, a credit, or, within your contract’s terms, walking away. See the due diligence section above and the Ask Steve answer on negotiating after inspection.
Negotiating after the inspection What happens if the appraisal is below the purchase price?
Options depend on your contract and loan program: renegotiate the price, challenge the value with supporting sales, or make up the difference. See the due diligence section above.
Who pays the buyer’s real estate agent?
In most Las Vegas purchases, the seller pays the buyer’s agent compensation out of the sale proceeds, negotiated as part of the deal. Since the 2024 commission changes, the amount is agreed in a written buyer representation agreement, and the buyer may be responsible if the seller does not pay it. Confirm who pays, in writing.
Do I need an agent to buy? Can I buy a home remotely?
Yes. Video walkthroughs, comparable sales, a licensed inspection, and the HOA documents make remote buying workable, and a live walkthrough can be arranged when timing allows.
Buying a home sight unseen What should I know about HOA communities in Nevada?
Most Las Vegas homes sit in an HOA. Review the dues, the rules, the association’s financial health, and the resale package before closing. Nevada law provides specific resale-package requirements for common-interest communities. See the due diligence section above and the Ask Steve answer on HOAs.
What to know about HOAs How long does closing typically take?
A typical financed purchase closes in about 30 to 45 days from the accepted offer, depending on the lender, the contract, and the calendar. Cash can close faster, and new construction follows the builder’s timeline.
Timeline from offer to close When do I receive the keys?
Keys are released when possession occurs, which follows recording and the possession terms in your contract. Signing documents does not automatically mean keys are handed over that moment. See the closing section above.
What is the difference between closing costs and a down payment?
The down payment is the portion of the purchase price you pay from your own funds and becomes equity in the home. Closing costs are the separate lender, title, escrow, recording, and prepaid fees paid at closing. See the financing section above.
About Steve Lockhart
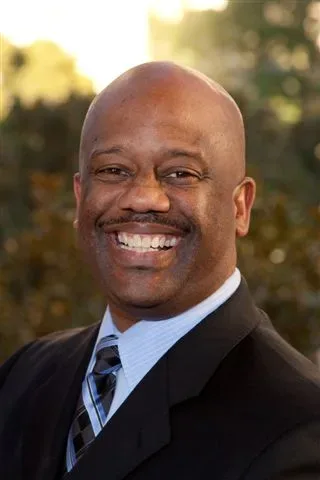
A Strategic Partner for One of Your Biggest Financial Decisions.
Steve Lockhart brings extensive executive management experience and a structured real estate advisory approach to helping buyers navigate the Las Vegas market.
Through The Lockhart Method™, buyers receive guidance focused on preparation, market intelligence, clear communication, thoughtful evaluation, and strategic negotiation.
Steve Lockhart is a Las Vegas REALTOR® with First Mutual Realty Group, Nevada license S.0194053, and a member of the National Association of REALTORS.
Meet Steve LockhartThe next step
Ready to Make Your Next Move With Confidence?
Whether you're just beginning to explore your options or preparing to purchase, the right strategy starts with understanding your goals, financial position, and priorities.
This guide is for general information only and is not legal, tax, lending, or inspection advice. Nevada-specific references are general summaries; review your contract and consult qualified professionals for your situation.