Waiting for mortgage rates to drop can cost you more than a higher rate. See how seller concessions and rate buy-downs get you into a Las Vegas home now.
You have been watching mortgage rates like they are a slot machine, waiting for that perfect number to drop so you can finally pull the trigger on a home in Henderson, Centennial Hills, or Summerlin West. Meanwhile, your rent just went up again. Your landlord just bought a new truck. And that $565,000 median-priced home you were eyeing six months ago? It is now $595,000. Here is the uncomfortable truth: waiting for rates to drop is costing you more than a higher rate ever will. Let me show you a different strategy, one that does not require you to time the market, predict the Fed, or sacrifice your financial future to your landlord's mortgage payment.
The short answer
Let's do some quick math. The median home price in Las Vegas in early 2026 is hovering around $565,000.
The Real Cost of Waiting
Let's do some quick math. The median home price in Las Vegas in early 2026 is hovering around $565,000. If you are waiting for rates to drop from 6.5% to 5.5% before you buy, you are gambling on two things: that rates will actually drop that far, and that home prices will not climb while you wait. Here is what usually happens in the Las Vegas housing market: for every 1% drop in rates, buyer demand surges. When demand surges, prices climb, fast. You might save $200 a month on your mortgage payment with a lower rate, but if that house went from $565,000 to $595,000 while you waited, you just added $30,000 to your loan, and you are starting from behind.
Plus, let's talk about rent. If you are paying $2,200 a month for a three-bedroom rental in Henderson, you are paying 100% interest. Every single dollar goes to your landlord's equity, not yours. That is $26,400 a year in pure expense with zero return.
What Is The Lockhart Method?
The Lockhart Method is not a gimmick or a loophole. It is a negotiation strategy I developed working with hundreds of Las Vegas buyers who were stuck in the same paralysis you are in right now. It is built on one core principle: instead of waiting for the market to give you a better rate, negotiate the seller into paying for one.
Here is how it works. When you make an offer on a home in the Las Vegas Valley, you ask the seller to contribute to a rate buy-down as part of the deal. This is also called seller concessions or seller-paid points. Instead of asking them to drop the price by $10,000, you ask them to put that $10,000 toward lowering your interest rate, permanently or temporarily.
Why This Works Better Than a Price Drop
A $10,000 price reduction saves you about $50 a month on your mortgage. A $10,000 rate buy-down can save you $150 to $250 a month, depending on the structure. It is simple leverage math, and most buyers do not even know to ask for it.
Here is the other advantage: sellers are often more willing to contribute to closing costs or rate buy-downs than they are to drop their asking price. Why? Because it does not feel like they are losing money in the same way. It is a psychological win that benefits both sides.
How The Lockhart Method Works in Practice
Let's walk through a real-world scenario using a home in Centennial Hills listed at $575,000.
Traditional approach: you offer $565,000, the seller counters at $570,000, you are at 6.5% interest, and your monthly payment (principal and interest) is about $3,600.
Lockhart Method approach: you offer $575,000 at full price, you request $12,000 in seller concessions toward a rate buy-down, the seller agrees because they got their price, you buy your rate down to 5.5%, and your monthly payment (principal and interest) is about $3,260. You just saved $340 a month, $4,080 a year, without waiting for the Fed to move. And you are building equity from day one instead of paying rent. Even better, if home values appreciate by just 3% annually, your $575,000 home is worth $592,250 in one year. That is $17,250 in equity you would not have earned while renting.
Why Sellers Agree to This
You might be wondering why a seller would give you $12,000 toward your rate when they could just pocket it. A few reasons:
- Days on market matter. Sellers do not want their home sitting. Every extra week on the market costs them money: mortgage payments, utilities, stress. A clean offer at asking price with a simple concession often beats a lower offer with no strings attached.
- Appraisal protection. If the home appraises at $575,000 and you offered $575,000, the deal moves forward cleanly. If you offered $565,000 and it appraises at $570,000, now you have a problem. Full-price offers with concessions reduce appraisal risk.
- Tax strategy. Some sellers prefer to maintain their list price for tax and reporting reasons, even if they are contributing back at closing. This is especially common with investment properties or estate sales.
The "What If Rates Drop Later?" Question
I hear this all the time: "But Steve, what if I buy now and rates drop to 4% next year? Won't I be stuck?" No. You can refinance. And here is the beauty of The Lockhart Method: you got into the home at a price that locks in today's value, and you have been building equity the entire time. When rates do drop, if they drop, you refinance into the lower rate and keep the equity you have built.
Compare that to waiting another year: you spent another $26,400 in rent, home prices climbed another 3 to 5%, and you are starting from scratch with a higher purchase price. Even if you refinance in two years and pay closing costs again, you are still ahead because of appreciation and the equity you built while living in your own home.
How to Use The Lockhart Method in Your Offer
Step by step:
1. Get pre-approved with a lender who understands rate buy-downs in Las Vegas. Not all lenders structure rate buy-downs the same way. You need one who can calculate temporary versus permanent buy-downs and show you the real monthly savings.
2. Work with a Realtor who negotiates beyond price. This is where I come in as your Las Vegas buyer agent. Most agents are trained to negotiate price. I am trained to negotiate outcomes. There is a difference.
3. Structure your offer strategically. Do not lowball the seller and then ask for concessions. Offer at or near list price, and request the concessions as part of a clean package. Sellers are far more likely to agree when they feel like they are winning too.
4. Use inspection and appraisal as leverage points. If the home needs minor repairs or appraises slightly under, you can renegotiate concessions instead of price. This keeps the deal moving and gets you the rate relief you need.
5. Close and start building equity. Once you are in, you are done paying rent. Every mortgage payment builds equity. Every year of appreciation works in your favor.
The Neighborhoods Where This Works Best
The Lockhart Method works across all Las Vegas submarkets, but I am seeing the most traction in areas where inventory is balanced and sellers are motivated without being desperate. Right now that includes Centennial Hills (family-friendly, newer builds, strong appreciation history), Henderson and Green Valley (established community, great schools, stable values), and Summerlin West (premium location, access to parks and trails, high buyer demand).
Whether you are shopping for Centennial Hills homes for sale, comparing Henderson and Green Valley homes, or exploring Summerlin West real estate, the same strategy applies. These areas have a healthy mix of move-up buyers and sellers who are relocating or downsizing, which means they are often flexible on concessions if it means a fast, clean close.
What About New Construction?
New construction is trickier, but not impossible. Many Las Vegas builders are offering their own rate buy-downs or incentives right now to move inventory, and new construction incentives in Las Vegas can often be stacked with other credits. The key is understanding what is negotiable.
I work directly with builder representatives to stack incentives in your favor, and sometimes you can combine a builder rate buy-down with additional closing cost credits. If you are looking at new builds in Centennial Hills or the northwest valley, let's talk strategy before you walk into the sales office. Builder representatives work for the builder, not you.
FAQ: The Lockhart Method Explained
Q: Is this legal? A: Yes. Seller concessions are a standard part of real estate transactions and are fully disclosed to all parties.
Q: How much can a seller contribute? A: Depending on your loan type, sellers can typically contribute 3 to 6% of the purchase price toward closing costs, which includes rate buy-downs.
Q: Does this work with FHA or VA loans? A: Absolutely. In fact, VA buyers can often negotiate higher seller concessions, making this strategy even more powerful.
Q: Will asking for concessions make my offer weaker? A: Not if it is structured correctly. A full-price offer with concessions is often stronger than a lowball offer with no concessions.
Q: What if the seller says no? A: Then we adjust. Maybe we negotiate a temporary buy-down instead of a permanent one. Maybe we target a different property where the seller is more motivated. This is where strategy and market knowledge matter.
Why I Built This Method
I did not invent seller concessions in Las Vegas. But I did systematize how to use them as a wealth-building tool for buyers who are tired of being told to wait and see. I am an AI Certified Real Estate Agent, which means I use data, market modeling, and predictive analytics to show buyers the real financial impact of their decisions.
The Lockhart Method is the result of running hundreds of scenarios, watching buyers win, and seeing renters lose, not because they could not afford to buy, but because they were waiting for perfect conditions that never came. If you are ready to stop renting and start building equity, I can show you exactly how this works for your situation. I also work with HomeOffersEZ, a cash offer platform that gives you even more negotiation leverage in competitive markets (affiliate link disclosure: I may earn a commission if you use this service, at no cost to you).
The same thinking applies on the seller side: compare your selling options, start with an honest home value estimate, or read the seller strategy page. You will also find the full library of articles on the blog.
The Bottom Line
Renting is 100% interest. Waiting for Las Vegas mortgage rates to drop is a gamble. Home prices do not pause while you are on the sidelines.
The Lockhart Method gives you a way to buy now, lock in today's prices, build equity immediately, and still benefit when rates drop later, because you can always refinance. You do not need permission from the Federal Reserve to start building wealth. You just need a Las Vegas home buying strategy that works in the real world.
Let's talk. I'll show you the math on your specific situation, walk you through how the concessions work, and get you into a home in Henderson, Centennial Hills, or Summerlin West, without waiting for a market miracle. Ready to stop renting and start building equity? Call me at 702-763-9333 or email steve@stevelockhartrealtor.com.
This article is general information and not financial, lending, or tax advice; rates, programs, and loan limits change and vary by lender and situation, so talk to a qualified mortgage lender and your own advisors before making a decision.
About the author
Written by Steve Lockhart, Las Vegas REALTOR® with First Mutual Realty Group (Nevada license S.0194053), member of the National Association of REALTORS, and creator of The Lockhart Method™.
This article is general information only and is not tax, legal, or financial advice. Your situation deserves a conversation with the right professionals before you act.
Related Articles
More on Buyer Education
The First-Time Buyer Blueprint for Las Vegas: High-Tech, High-Touch
Buying your first Las Vegas home? Use AI-assisted search, comps, and a clean offer strategy to compete without guessing. Start with a free session.
 Buying
New Listing in Las Vegas
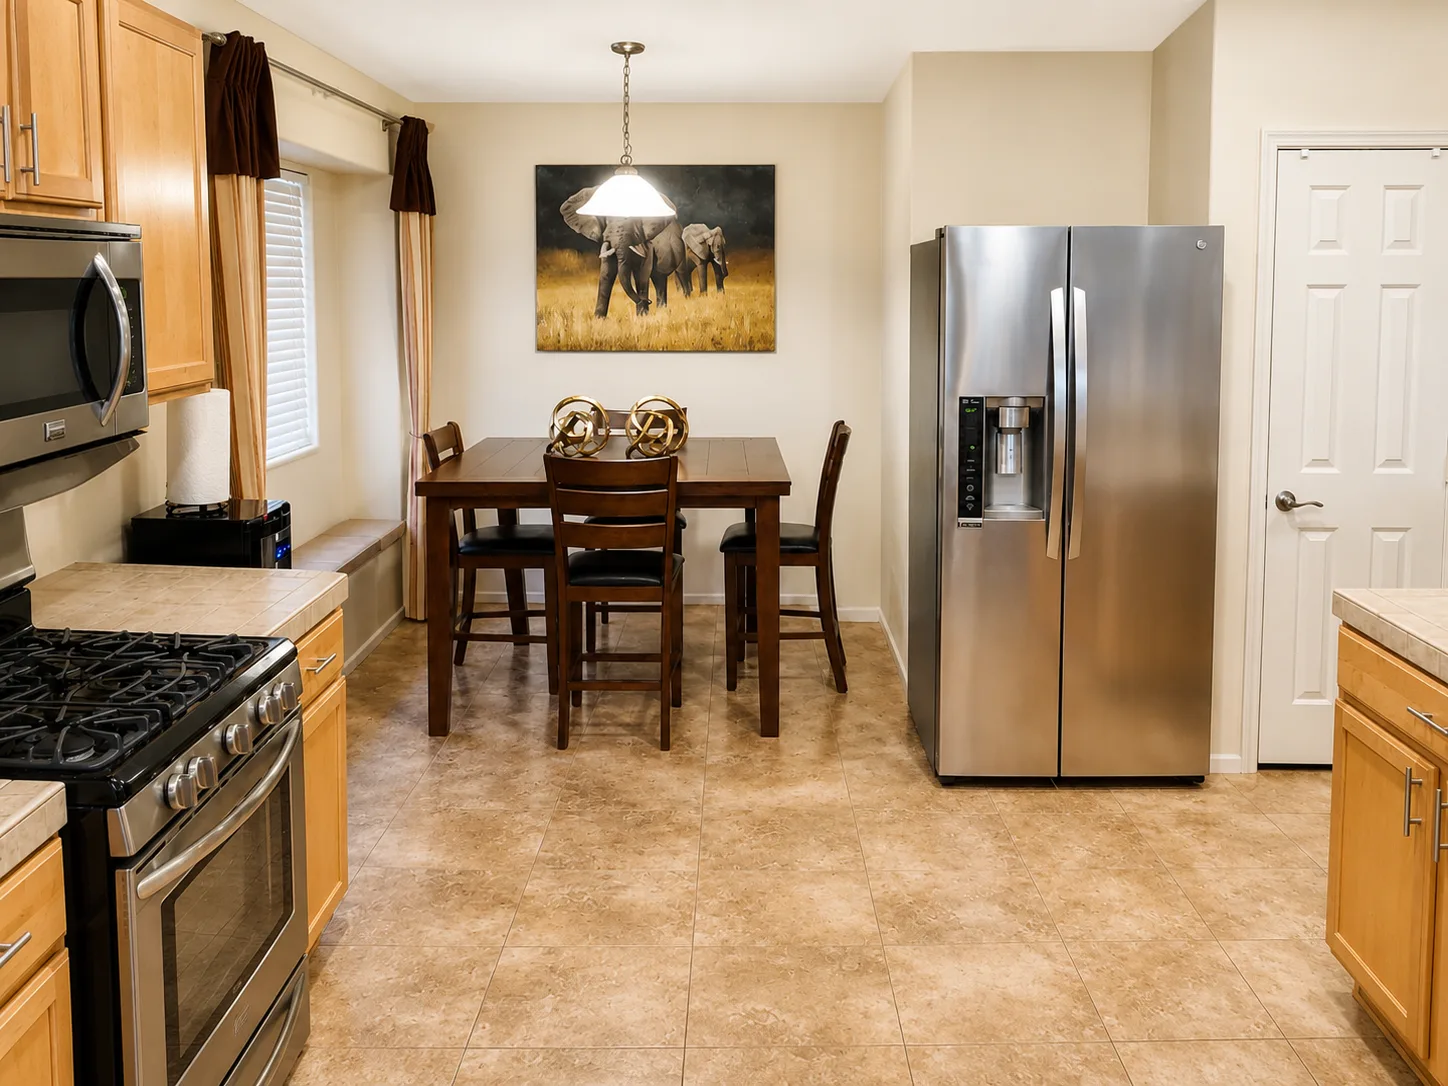
7642 Plunging Falls Dr, Las Vegas, NV 89131 is now on the market and available for showings. Steve Lockhart of First Mutual Realty Group represents the sale.
 Buying
VA Loans and Buying Near Nellis Air Force Base
The VA loan is one of the strongest home buying tools in the country, and it deserves a strategy, not just a checklist. How it works and how we pair it with your next address.
The next step
Run the rate buy-down math on your offer
A strategy call is where The Lockhart Method starts: we look at your price range, your loan options, and what seller concessions can do for your monthly payment in Henderson, Centennial Hills, or Summerlin West. No pressure, nothing to sign.
Schedule a Consultation